High Yield Bonds Rally, Long Duration Treasuries Sell off
Investors are pouring into risky junk bonds as an alternative to low-interest treasury bonds, sending junk bond yields to historic lows. The average yield on high yield bonds dipped below four percent for the first time in history Monday, down from […]

US Treasury, Source, Shutterstock
- Investors are paying up for high yield bonds, even as treasury yields are rising
- The average yield on high yield bonds dipped below four percent for the first time in history Monday
Investors are pouring into risky junk bonds as an alternative to low-interest treasury bonds, sending junk bond yields to historic lows.
The average yield on high yield bonds dipped below four percent for the first time in history Monday, down from nearly 12 percent in April 2020. 30-year Treasuries rose to two percent Monday before settling at 1.93 percent Tuesday afternoon.
“The high yield bond market is almost a general proxy for equities, telling you that investors don’t see any risk,” said Steve Van Metre, founder of Steve Van Metre Financial.. “When high yields or junk yields are low, investors are telling you that there is minimal risk, and I disagree. I think there is an immense amount of risk out there.”
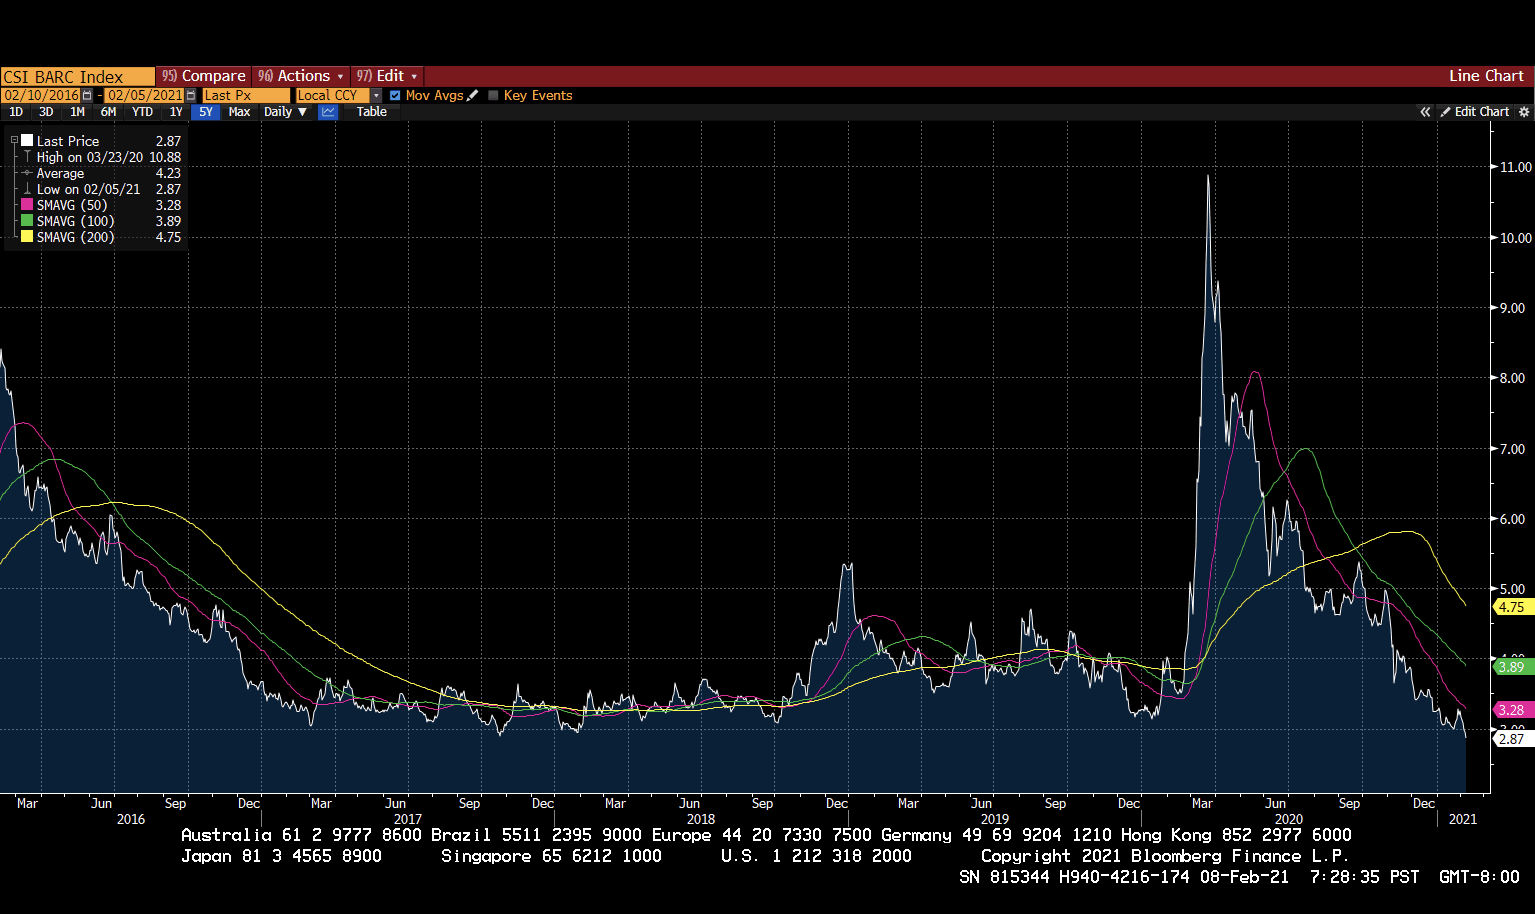 [High Yield Corporate Bond Spreads minus 10-Year Treasury Yield] Source, Bloomberg
What is happening in the high yield space, Van Metre said, is investors are chasing four percent to five percent junk yields because they perceive there is no default.
“In treasuries, there is a lot of speculative selling on the long end of the curve, and we’ve seen that since August,” said Van Metre. “We see that because there’s a belief that there’s going to be reflation and high rates of inflation due to the overwhelmingly false belief that the Fed actually is and can print money, which they cannot.”
Investors are front running this alleged money printing at the long end of the curve, said Van Metre, but the short end of the curve reveals something completely different.
There’s a collateral shortage in the banking system due to too much liquidity, which means that everything from three-year to 12-months-and-under treasury bill yields are all falling, said Van Metre. There is a high demand from banks for high quality, pristine collateral, and there isn’t enough in the market for it.
“This tells you that all these speculators who have been selling [the long duration treasuries] since August completely don’t understand what’s going on in the system,” said Van Metre. “They’re just front-running what they hope to be a big trend.”
Van Metre expects that as the Treasury starts to draw down its immense cash balance, likely through stimulus spending, there is a risk that the front of the curve will dip negative.
“If the front of the curve goes negative, which I believe it can, and even Yellen has stated that it is possible that it will, that will cause a massive unwinding on the long end of the curve and drag it lower because the long end always follows the front end,” said Van Metre.